
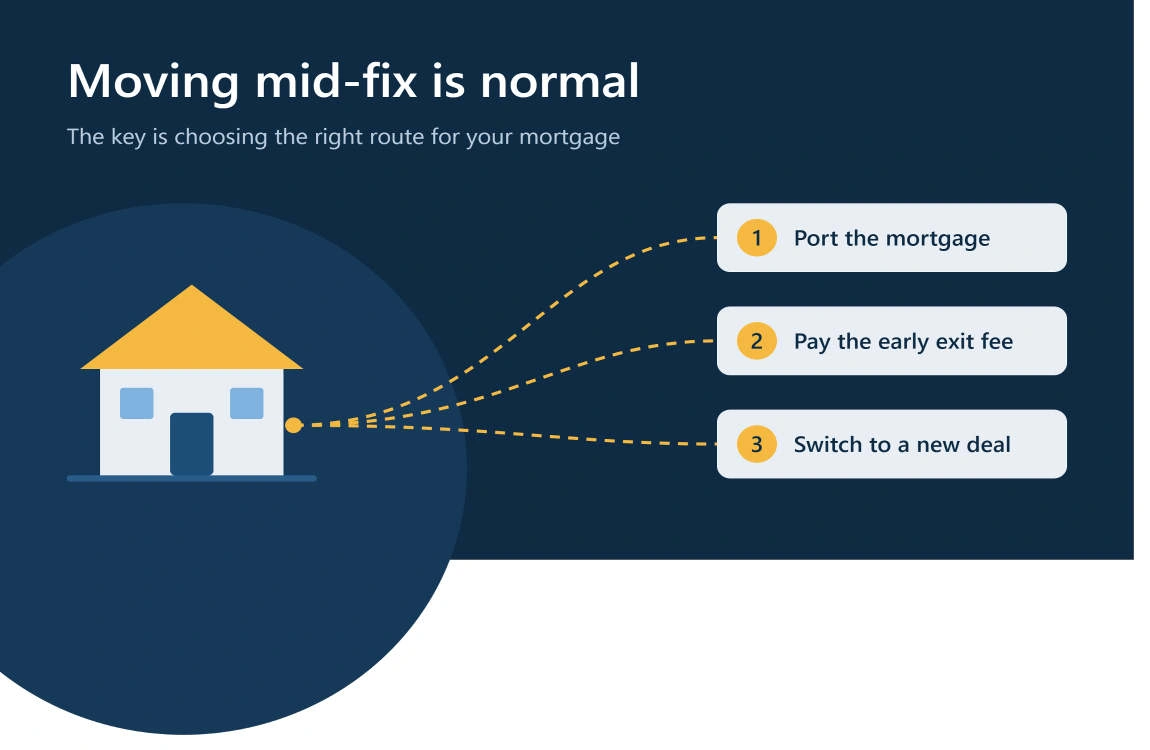
Can I move house on a fixed rate mortgage? Yes, you can. Being in the middle of a fixed deal doesn’t stop you selling your home and buying another. What it changes is the cost. Leave a fixed deal early without a plan and you will usually face an early repayment charge (ERC). Plan it properly and you can often avoid that charge altogether by taking your deal with you, which is known as porting.
What Is an Early Repayment Charge (ERC)?
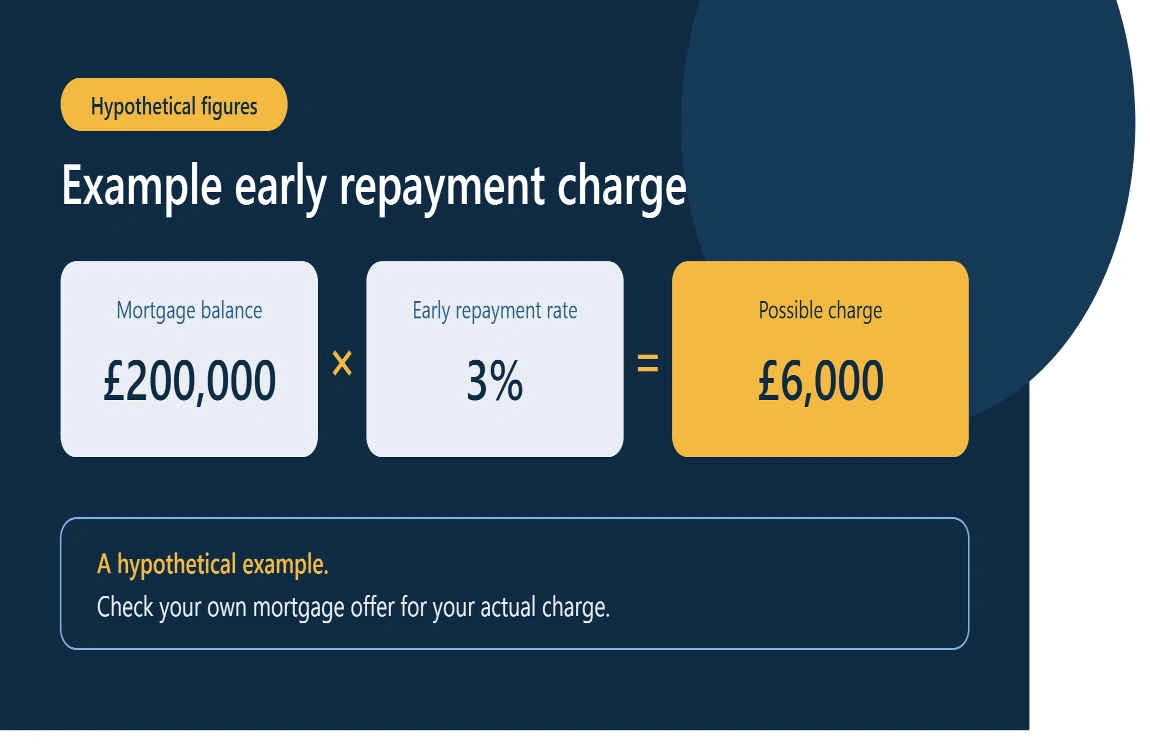
An ERC is a fee your lender can charge if you pay off all or part of your mortgage during the deal period. Lenders price fixed deals on the assumption that you’ll keep them for the full term, so they charge you if you leave early. The Financial Ombudsman Service describes it as a fee you might be asked to pay if you reduce the amount you’ve borrowed, for example by real estate paying a lump sum.
How much could it be? NerdWallet UK notes that ERCs are typically between 1% and 5% of the outstanding balance, and the exact figure depends on your lender and product. Your mortgage offer document will set out your own charges.
What Is Porting a Mortgage?
Porting means taking your existing mortgage deal to your new home. You keep your interest rate, and the end date of your fixed period stays the same. Danske Bank says that when you port, the outstanding balance, interest rate and fixed-rate end date stay the same, though you may be able to change the remaining term.
One thing surprises many people: porting is not a simple transfer. Halifax describes the process as paying off the old mortgage and taking out a new one on the new house at the same rate. In practice, that means a new application, a valuation of the new property and an affordability check. Yorkshire Building Society warns that if your circumstances have changed you may need to reapply and might no longer be eligible, and that you will still pay valuation and legal fees.
Will You Pay an ERC When You Port?
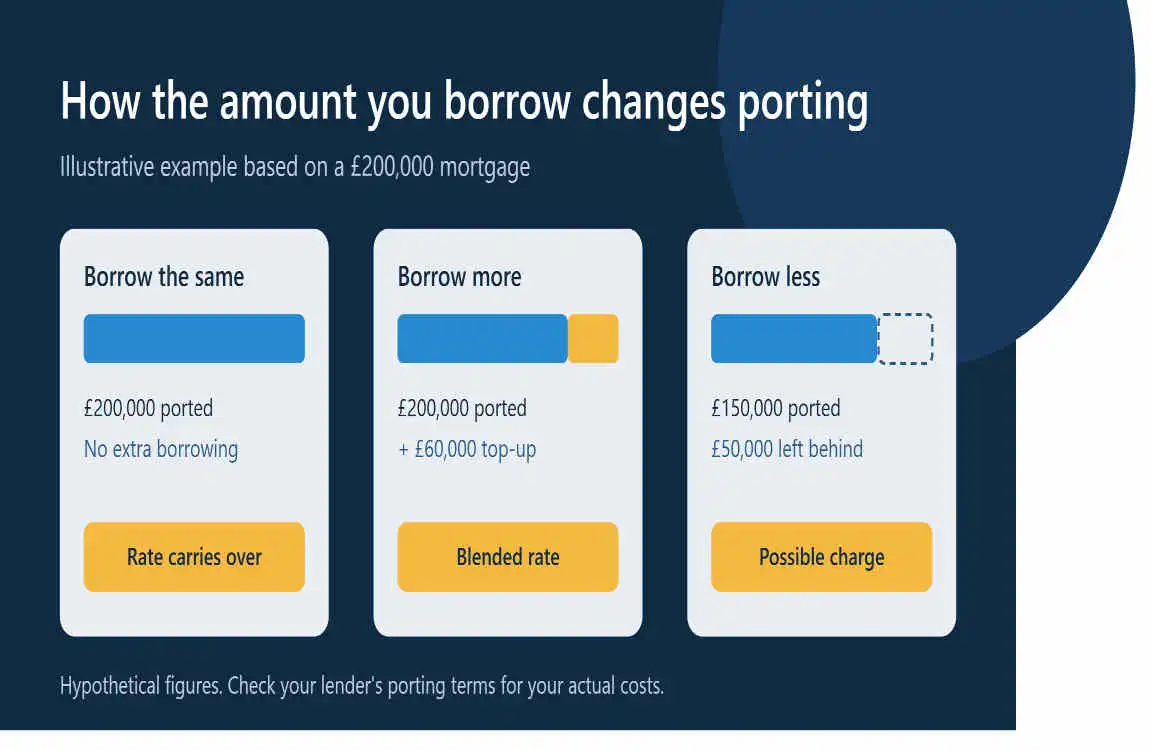
It depends on how much you borrow on the new property compared with your current balance.
You borrow the same amount
Generally no ERC. Santander says you won’t pay an ERC to port a fixed rate deal for the same amount, and the same applies if you sell and buy on the same day, unless you borrow less.
You need to borrow more
You can usually port your current deal for the existing balance, then take a second product for the extra amount at whatever rates are on offer at the time. The result is a blended arrangement: part of your borrowing stays on your old rate and the top-up sits on the new one.
You want to borrow less (downsizing)
This is where charges often appear. You can still port, but lenders typically charge an ERC on the part of the mortgage you don’t take with you. Halifax confirms you may have to pay an ERC on the difference. Overpayment allowances can soften this, since many mortgages let you overpay a set amount each year without charge, commonly up to 10% of the balance, as Moneyfacts points out.
When Porting Isn’t Possible or Doesn’t Make Sense
- Your product isn’t portable. Most fixed deals are, but not all. Your offer document will say, so check it before you list your luxury homes.
- You fail the new affordability check. Porting is treated as a fresh application, so a change in income, credit record or outgoings can affect the outcome.
- The new property doesn’t meet lending criteria. The lender must be happy with the valuation and the type of property.
- Your current rate is higher than what’s now available. If market rates have fallen, paying a modest ERC and moving to a cheaper deal can sometimes work out better. Work out the numbers before deciding. Brokers usually have calculators for this, and Unbiased explains why ERCs can change how worthwhile switching is.
Timing Matters More Than People Expect
Lenders set their own rules on timing, and getting this wrong is a common reason people pay a charge they could have avoided. Some points to check with your lender:
- Order of events. One lender, RBS, says your new mortgage application must be completed before you redeem your current mortgage.
- How long your offer lasts. Danske Bank refunds the ERC if your purchase completes within its 180-day offer period or before the fixed rate ends, whichever is sooner. Other lenders have different windows.
- Selling before buying. If there’s a gap between the two completions, ask whether you’ll be charged and whether it can be refunded later.
- Close to the end of your fix. Santander, for instance, refunds the ERC in some cases where only a few months of the fixed rate remain. Ask whether similar terms apply to you.
Costs to Budget for Even When You Port
Porting can protect you from an ERC, but it doesn’t make moving free. You’ll still need to allow for:
- Stamp duty. Halifax confirms you still pay stamp duty when porting, based on the price of the new home and where it is.
- Valuation and legal fees. As noted above, these still apply when you port.
- Any arrangement or product fees on a top-up product if you borrow more.
- Estate agent and removal costs, which sit outside the mortgage entirely.
Smart Ways to Avoid an ERC Altogether
- Port wherever it’s possible and keep the amount the same or higher.
- Time your move for after the fixed period ends. The charge generally stops applying once the deal expires, as haart explains.
- Use your overpayment allowance before completion if you’re downsizing, to reduce the amount subject to a charge.
- Choose a deal with low or no ERC next time if you think you might move within a few years. NerdWallet UK notes that some fixed deals have no early repayment charge, though the trade-off can be a higher rate.
- Get advice early. A broker or the lender’s modern home-mover team can calculate whether porting or a new deal is cheaper in your case.
Frequently Asked Questions
Can I move house on a fixed rate mortgage without paying a penalty?
Often yes. If your mortgage is portable and you borrow the same amount or more, many lenders won’t charge an ERC. Borrowing less usually triggers a charge on the part you don’t port.
Is porting automatic?
No. You must apply, and the lender will assess affordability and value the new property. Approval isn’t guaranteed.
What if my new home costs more?
You can typically port your existing balance and take an additional borrowing product to cover the shortfall, at the rate currently available to you.
What if my mortgage isn’t portable?
Then your options are to wait until the fixed period ends or repay early and pay the ERC. Check the maths with an adviser, because the long-term savings from a new deal can sometimes outweigh the charge.
Do I still pay stamp duty if I port my mortgage?
Yes. Stamp duty depends on the property you buy, not on how it’s financed.
How much is a typical early repayment charge?
Commonly 1% to 5% of the outstanding balance, depending on your lender and deal.
