
It’s one of the most common myths in international property circles: spend enough on a UK home and the right to live there for good will follow. Plenty of buyers also hear that holding the property inside a company is the smarter, more private way to do it, which is why “how to buy a house under a corporation” has become such a popular search.
Does buying a house in the UK give you residency?
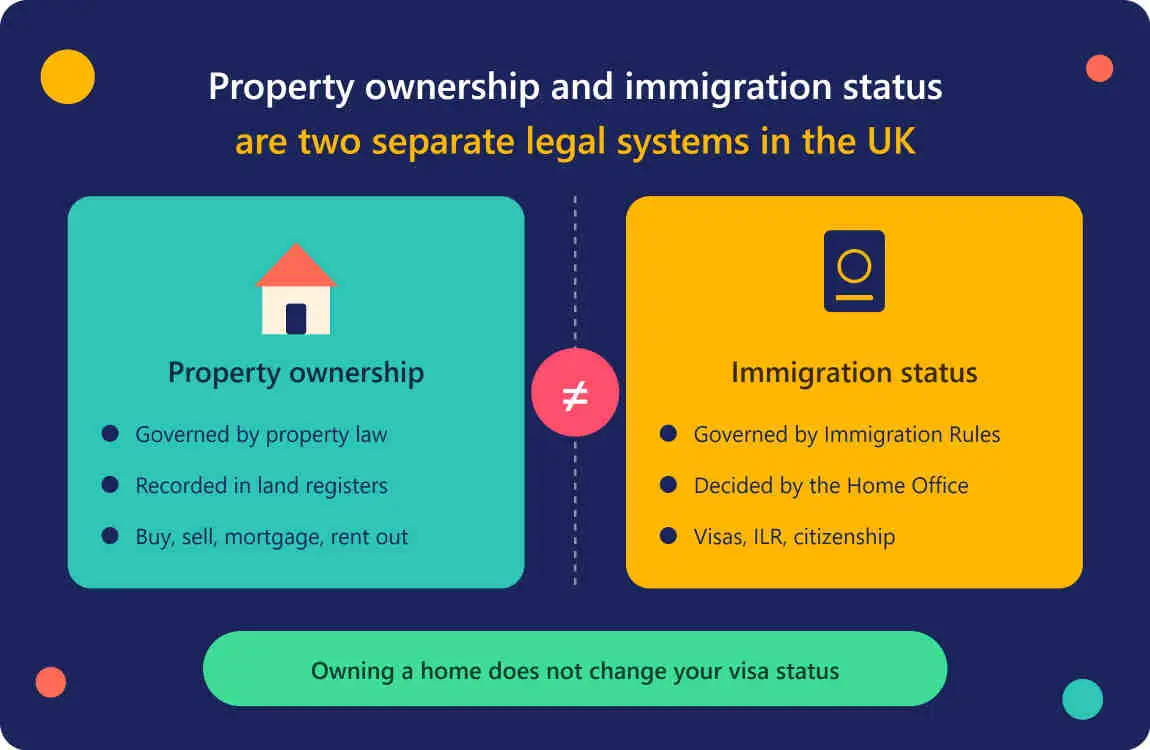
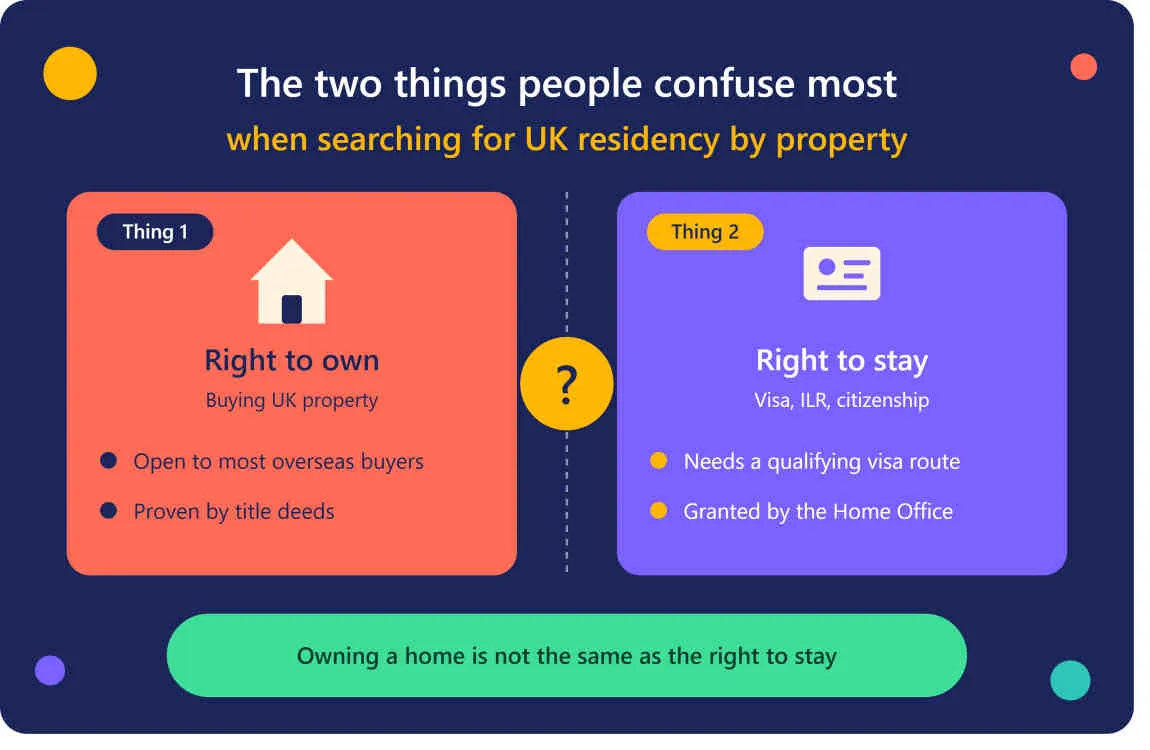
Immigration lawyers are unusually unanimous on this one. Property ownership and immigration status operate in entirely separate legal frameworks, according to London firm Gherson, and owning a dream home doesn’t grant the right to live in it, extend your time in the country or strengthen a visa application. Birketts LLP is equally blunt in its own briefing, noting that buying a house does not equate to the right to reside in the UK. The specialist publication Free Movement puts it as a single sentence worth remembering: buying property does not create immigration rights.
The good news is that the reverse is also true. There are no restrictions on purchasing property in the UK because of nationality or visa status, so visitors and people living overseas can legally buy. The catch is practical rather than legal. If you only hold a visitor permission, you can own the house design but you can’t simply move in and stay.
What “permanent residency” actually means in the UK
The UK doesn’t really use the phrase “permanent residency” the way some countries do. The equivalent is indefinite leave to remain (ILR), also called settlement: the right to live and work in the UK without time limits. It’s earned through time spent on an eligible visa, not through assets.
For many work routes the standard qualifying period has been five years. That’s the part people are watching right now. Under the Government’s “earned settlement” proposals, the baseline wait would double to ten years for most applicants, with some people able to shorten it based on factors such as earnings and public service. The consultation closed on 12 February 2026, and as of early October 2026 the move from five to ten years is still a proposal and not yet in the Immigration Rules. The Home Secretary has told MPs the final policy, including any transitional arrangements, will be published “later this year”.
Parliament has not been shy about pushing back. A Commons Library briefing notes that the consultation proposes applying the changes to people already in the UK who don’t yet hold ILR, and the Real Estate Home Affairs Committee has urged ministers to get the detail right rather than rush it. Because the rules are moving, always check the latest position on GOV.UK before relying on any timeline.
What happened to the UK “golden visa”?
Before 2022, wealthy overseas investors could qualify for the Tier 1 (Investor) visa, which involved putting millions into UK investments. That route is gone. The Home Office states that from 16:00 GMT on 17 February 2022 the Tier 1 (Investor) route closed to new initial applications. Even in the old scheme, the qualifying investments were government-approved assets such as UK company capital, not a home you live in.
Anyone selling a “buy a house, get a visa” package today is either misinformed or hoping you don’t check.
So can property help your immigration case at all?
Only indirectly. Owning a home can show stable accommodation or financial standing in some situations, but it’s supporting evidence, never an entitlement. A buyer on a time-limited visa should also think about the exit: if your permission ends, you may have to sell on someone else’s timetable. Lenders add another layer, since a temporary visa is treated as a risk when you apply for a mortgage.
How to buy a house under a corporation in the UK
Buying through a company is perfectly legal and quite common, particularly for landlords, investors and families who want a ring-fenced structure. Just don’t mistake it for a residency strategy. If you’re set on it, here’s how to buy a uk house under a corporation, step by step.
Decide which kind of company you’re using
A UK-incorporated limited company (often a single-purpose “SPV”) is the usual choice for landlords and investors. Some buyers prefer an existing company formed abroad. That works, but it triggers extra registration rules, covered next.
Register an overseas entity if the company is foreign
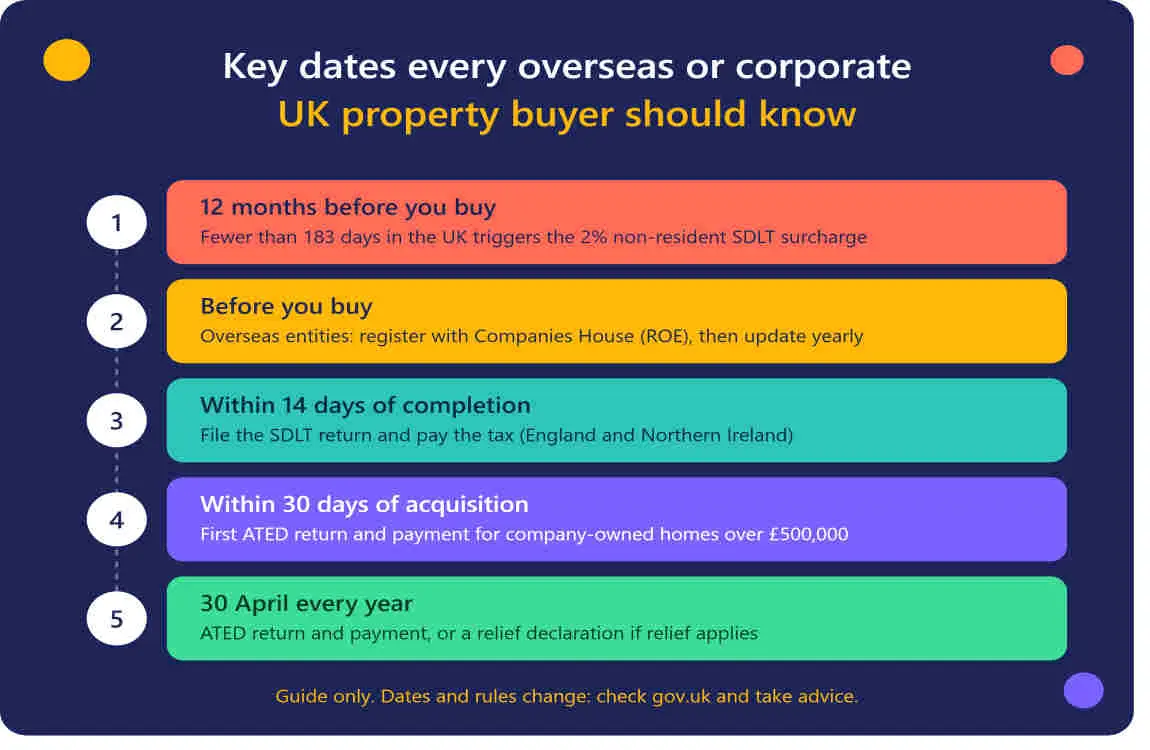
If the buyer is a company governed by the law of another country, it must be on the Register of Overseas Entities before it buys. The Government’s own guidance explains that the register exists so an overseas entity can buy, sell or transfer property or land in the UK, and you’ll need to disclose who the beneficial owners or managing officers are. Once registered you receive an Overseas Entity ID, which you hand to HM Land Registry for any purchase, sale, lease or charge. Details of the entity and its beneficial owners are, in general, available to the public on the online register, so privacy isn’t the benefit people sometimes assume it is.
Sort the funding
Cash buyers have it easy. Anyone borrowing will normally need a lender that deals with company borrowers, and directors are often asked for personal guarantees. Lenders also look closely at where the money comes from, so keep clean records of source of funds from day one.
Budget honestly for Stamp Duty Land Tax
This is where corporate buying gets expensive. Under HMRC’s rules, Stamp Duty Land Tax is charged at 17% on residential properties costing more than £500,000 bought by companies and other non-natural persons. The increase from 15% applies to transactions with an effective date on or after 31 October 2024, as set out in the Government’s policy paper on the change. Below £500,000, the higher rates and a 5% company surcharge can apply instead. A further 2% surcharge applies to certain non-UK resident buyers, which includes some UK companies controlled by non-residents. Accountancy group Forvis Mazars notes the combined flat rate for non-UK purchasers can reach 19% of the acquisition value.
The reliefs matter, though. A genuine property rental business or developer may qualify for a relief or exemption, but each has strict conditions and has to be claimed correctly. This is the single biggest area where a good tax adviser pays for themselves.
Complete the purchase
Use a conveyancing solicitor who regularly acts for companies. Expect enhanced ID and anti-money-laundering checks, especially for overseas structures. After completion, submit the SDLT return and pay within HMRC’s deadline (currently 14 days after completion), then register the title at HM Land Registry.
Keep up with annual obligations
Owning through a company isn’t a one-off. You’ll file company accounts and tax returns, and if the property is worth over £500,000 you may also need to deal with the Annual Tax on Enveloped Dwellings (ATED). Law firm Burges Salmon describes ATED as a charge on residential property above £500,000 held within a corporate “envelope”. Several reliefs exist (for example for property rental businesses), but you generally still have to file a return to claim them.
Corporate ownership and your immigration status
A company can own a house. It can’t hold a visa, and it can’t live in the property. Your right to be in the UK still depends on your own immigration permission, so a company structure does nothing to shorten a qualifying period or replace a visa.
If you plan to live in a home your company owns, speak to an accountant first. Living in company property can create extra tax questions, such as a taxable benefit for directors, and the 17% SDLT rate was designed to discourage exactly this kind of “enveloping” of homes.
What’s trending: higher costs for high-value homes
The cost of holding expensive UK property is heading up. From April 2028 the Government plans a High Value Council Tax Surcharge on residential property in England worth £2 million or more. Official papers describe it as a new charge on owners of residential property taking effect in April 2028, payable by the owner rather than the occupier. Consultation material has also raised the question of an extra premium for non-UK resident owners and how complex ownership structures should be treated, so corporate and overseas buyers should keep a close eye on the final rules.
A smarter order of operations
- Sort your immigration route first. Work out which visa fits your real plans, and how long it could take to reach settlement under the rules in force when you apply.
- Decide whether you need a company at all. For a main home, personal ownership is usually far cheaper in tax. A company tends to make sense for letting or development, not for living.
- Get specialist advice from two people. An immigration solicitor (SRA-regulated) or OISC-regulated adviser, and a property tax accountant, ideally talking to each other.
- Run the numbers on the whole holding period. SDLT, ATED, accounts, lender costs and the 2028 surcharge if your home property is worth £2 million or more.
- Keep a source-of-funds file. Lenders, solicitors and Companies House all care about it.
Frequently asked questions
Can I get a UK visa by buying a house?
No. There’s no property-based visa. Immigration status comes from formal routes such as work, family or business, and the old Investor route is closed.
Can a foreigner buy a house in the UK through a company?
Yes, there’s no nationality restriction on owning UK property. A foreign company must first register as an overseas entity with Companies House and obtain an Overseas Entity ID.
How much Stamp Duty does a company pay on a UK house?
For homes over £500,000, companies pay a flat 17% unless a relief or exemption applies. Non-UK resident buyers can face an extra 2% surcharge.
Is the 10-year route to settlement law yet?
Not as of early November 2026. It remains a proposal while the Home Office finalises its policy, so check GOV.UK before making plans.
The bottom line
Buying a house in the UK won’t secure you permanent residency, whether you buy personally or work out how to buy a house under a corporation. Property is an asset; residency is a legal status you earn through the immigration system. Get the visa strategy right first, then choose the ownership structure that makes tax sense, and you’ll avoid the expensive mistakes that catch out so many overseas buyers.
